Counter-UAV (C-UAV) Market to reach US$24.68bn
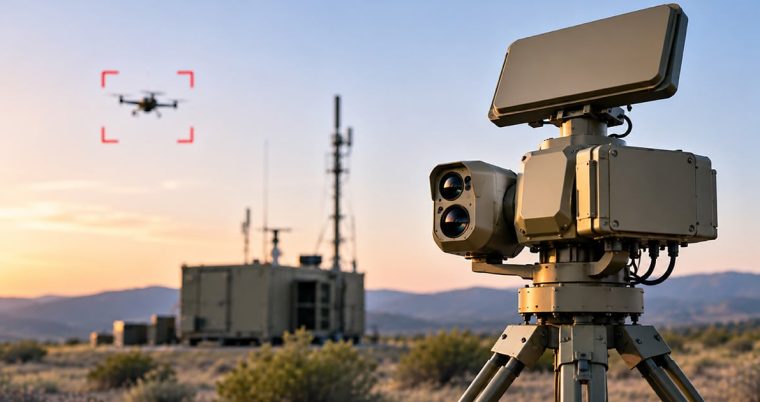
The global counter-UAV (C-UAV) market is expected to expand from US$6.07 billion in 2027 to US$24.68 billion by 2037, a 15.1% CAGR over the forecast period. Procurement is moving from urgent stop-gap purchases to programmes of record as armed forces, homeland-security agencies and airport operators build layered detect, track, identify and defeat defences against low-cost drones.
The report covers offering, deployment configuration, system integration, application, technology and region, profiling 20 leading counter-UAV vendors and technology providers across a 460+ page study with 158 tables and 232 charts.
Key Market Growth Drivers & Industry Transformations
Combat-Proven Drone Warfare Accelerating Procurement: Operational experience in Ukraine and the Middle East has shown that low-cost drones can overwhelm conventional air defence. After drone incursions over Poland in September 2025, the European Commission advanced the European Drone Defence Initiative, with initial capability targeted for the end of 2026 and full functionality by the end of 2027. The threat is persistent rather than episodic, which sustains multi-year budgets and gives suppliers demand visibility across detection, tracking and defeat layers.
Homeland Security and Major-Event Protection Expanding Civil Demand: Legal reform is opening civil markets previously limited to detection. The Safer Skies Act, enacted in December 2025, extends counter-drone mitigation authority to trained state, local, tribal and territorial agencies, backed by a US$500 million counter-drone grant programme. The 2026 FIFA World Cup was the first large-scale civil test, with the FAA reporting more than 700 unauthorised drones seized across 11 U.S. host cities on 22 July 2026, supporting demand for portable and fixed-site detection, Remote ID integration and law-enforcement-grade mitigation tools.
Cost-Exchange Imperative Driving Directed Energy and Low-Cost Interceptors: Defending against drones worth a few hundred dollars with missiles costing far more is financially unsustainable. The UK Ministry of Defence ordered DragonFire laser systems from MBDA in a GBP 316 million contract on 20 November 2025, citing a cost of roughly GBP 10 per shot. Rafael’s Iron Beam entered operational delivery on 28 December 2025. Directed energy is the fastest-growing technology segment at a 17.2% CAGR over the forecast period, and Software and Services is the fastest-growing offering at a 16.1% CAGR as open C2 platforms, networked sensor grids and subscription models create recurring revenue.
Export Controls and Component Constraints Shaping Supply: China announced export controls on 13 categories of drone components in October 2026, effective November 2026, and the United States has imposed Section 232 duties on drones and listed components. The market is bifurcating between trusted-source suppliers for Western and allied buyers and diversified sourcing in non-aligned markets. Vendors with multi-regional production and qualified second sources for motors, batteries and semiconductors are best insulated from trade friction.
What This Means for the Market
The counter-UAV market is evolving from a niche defence requirement into a broad multi-domain capability spanning military, homeland security and critical infrastructure protection. As directed energy and low-cost interceptors change the economics of defeat, and as software and services grow faster than hardware, competitive advantage is migrating towards vendors with open architectures, proven analytics and the manufacturing scale to meet programme-of-record volumes. Supply chain localisation and export-control compliance are becoming as important as technology performance.
Scope of the Visiongain Report
Offering: Hardware and Equipment; Software and Services
Deployment Configuration: Fixed-Site Systems; Mobile and Vehicle-Mounted Systems; Portable and Handheld Systems
System Integration: Standalone Systems; Integrated Multi-Sensor Systems; Networked and Distributed Systems; Integrated Air Defence Systems
Application: Military Base and Force Protection; Border and Perimeter Security; Critical Infrastructure Protection; Airport and Airspace Protection; Other Applications
Technology: Detection, Tracking and Identification Systems; Command-and-Control (C2) and Sensor-Fusion Systems; Electronic Countermeasures; Directed-Energy Systems; Kinetic Defeat Systems; Other Technologies
Regions: North America; Europe; Asia-Pacific; Middle East and Africa; Latin America
National Markets: U.S., Canada, Germany, UK, France, Poland, Ukraine, China, India, Japan, South Korea, Australia, GCC, Israel, Brazil, Mexico, and Rest of regions
Competitive Landscape
Vendors are competing through framework contracts, production-capacity expansion, open-architecture software, multi-effector portfolios and partnerships with local producers. The competitive landscape spans established defence primes and specialist C-UAV companies.
- AeroVironment, Inc.
- Anduril Industries, Inc.
- Axon Enterprise, Inc.
- BAE Systems Plc
- CACI International Inc
- DroneShield Ltd
- Elbit Systems Ltd.
- Hensoldt AG
- Israel Aerospace Industries Ltd.
- Kongsberg Gruppen ASA
- L3Harris Technologies, Inc.
- Leonardo S.p.A.
- Lockheed Martin Corporation
- MBDA
- Northrop Grumman Corporation
- Rafael Advanced Defense Systems Ltd.
- Rheinmetall AG
- RTX Corporation
- Saab AB
- Thales SA
Recent Developments
- 21 October 2026: BAE Systems plans to raise APKWS guidance-kit production to as many as 35,000 units a year under a new U.S. DoD framework of up to seven years, strengthening low-cost guided-rocket supply for counter-drone kinetic defeat.
- 13 October 2026: RTX Corporation was awarded US$729 million of LIDS contracts covering KuRFS radar and Coyote effectors for the U.S. Army, Qatar and Jordan, including the first international sales of KuRFS and Coyote.
- 29 September 2026: Kongsberg signed an agreement with Oshkosh Defense Europe for PROTECTOR RS4 remote weapon stations with counter-UAS capability for the Netherlands, and announced a NOK 10 billion Belgian NASAMS order.
- 2 September 2026: Saab’s UK business delivered Giraffe 1X radars to the UK Ministry of Defence for Royal Air Force counter-drone operations in response to an urgent operational demand.
- 11 August 2026: Elbit Systems reported a record backlog of US$32.0 billion and unveiled a new airborne high-power laser, reflecting the move of directed energy from demonstration towards fielding.
Related Visiongain Market Reports
- Command and Control (C2) System Market Report 2027-2037
- Military Communications & COTS Market Report 2026-2036
- Undersea Defence Intelligence Market Report 2026-2036
About Visiongain
Established in 1998, Visiongain is an independent publisher of analyst-led market intelligence, delivering data-driven research, forecasts, and strategic insight across global industries and emerging markets. Visiongain supports evidence-based decision-making for investment, procurement, and long-term strategic planning.
Media Contact
press@visiongain.com
+44 (0)20 7336 6100
www.visiongain.com