Nuclear Fuel Market to reach US$72.24bn
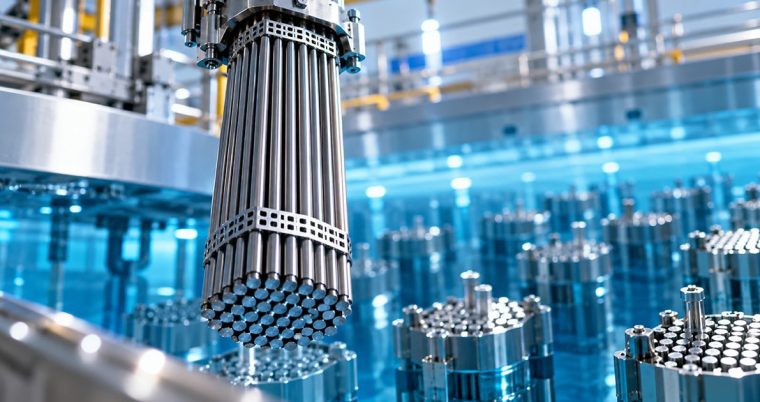
The Global Nuclear Fuel Market is projected to grow from US$36.08bn in 2027 to US$72.24bn by 2037, at a CAGR of 7.2%, according to the latest analysis from Visiongain.
Enrichment expansion, diversification away from Russian supply and demand for HALEU and TRISO fuels are redefining competition across the nuclear fuel cycle. Nuclear fuel has moved from a back-office commodity to a strategic supply chain: utilities are contracting further ahead, governments are funding domestic enrichment and fabrication, and advanced reactor developers are creating new demand for high-assay and TRISO fuels. The long-term uranium price reached US$96.50 per pound at the end of September 2026, compared with US$83.00 a year earlier.
Key Market Growth Drivers & Industry Transformations
Supply Security Reshaping the Front-End: Front-End activities account for more than four-fifths of market value. Policy is accelerating supply diversification: the U.S. bans Russian low-enriched uranium through 2040, with waivers until the end of 2027, and the DOE awarded US$900 million task orders each to Centrus, General Matter and Orano in January 2026. The UK banned Russian uranium imports from May 2026. On the supply side, Kazatomprom is operating below nominal capacity, with 2026 guidance of 27,500-29,000 tU on a 100% basis.
Advanced Fuels Creating a New Growth Layer: HALEU, ATF and TRISO fuels are among the fastest-growing segments, lifting their share of global revenue significantly over the forecast period. Advanced Fuel Forms and the HALEU & Advanced Fuel Supply Chain service segment are both projected to grow at double-digit CAGRs. Demand is being driven by advanced reactors, with fast and molten-salt reactor applications growing at faster rates than conventional pressurized and boiling water reactor demand. Supply is building: Centrus has produced more than 1,900 kg of HALEU at Piketon, Urenco and Antares Nuclear signed a multi-year commercial HALEU supply contract in May 2026, and Framatome gained NRC approval in June 2026 to fabricate TRISO fuel at Richland.
LEU+, Higher-Enrichment Fabrication and Fuel Recycling: Higher-enrichment products are entering the market. Urenco USA received NRC authorisation in September 2025 to enrich to just under 10% U-235, GNF holds approval to fabricate fuel of up to 8% enrichment, and Framatome has approval for just under 10% at Richland. The NRC has accepted Global Laser Enrichment’s licence application for the Paducah Laser Enrichment Facility, which aims to begin re-enriching DOE depleted uranium tails no later than 2030. Back-End activities are growing, with Spent Fuel, Reprocessing & Recycled Fuel services projected to increase over the forecast period. The DOE awarded US$19 million for recycling technologies in February 2026, a House subcommittee advanced the Nuclear REFUEL Act on 14 July 2026, and Japan is targeting completion of the Rokkasho reprocessing plant in fiscal 2026.
Market Growth Across Major Regions: Asia-Pacific is projected to be the largest and fastest-growing region, driven by long-term procurement by emerging nuclear economies such as India, where Cameco signed a nine-year agreement in March 2026 for nearly 22 million pounds of U3O8. Middle East & Africa and North America are also projected to record strong growth. Europe’s expansion reflects the transition to non-Russian VVER fuel, including Germany’s July 2026 approval of the expansion of Framatome’s Lingen plant. Latin America is projected to grow at a more moderate pace from a smaller base.
What This Means for the Market
The nuclear fuel market is evolving from a Russia-dependent, commodity-led supply chain towards a more diversified, security-driven and technology-differentiated one. Higher-enrichment fuels, new enrichment and fabrication capacity, recycling and advanced reactor demand, together with sanctions and long-term contracting, are increasing the strategic importance of fuel supply. Suppliers that combine secured uranium, licensed capacity across the fuel cycle and non-Russian supply credentials are best placed to address a broader range of utility and advanced-reactor requirements.
Scope of the Visiongain Report
By Fuel Cycle Stage: Front-End; Back-End.
By Fuel Type: Conventional Uranium Fuel; Advanced & High-Assay Fuel (HALEU, ATF, TRISO); Recycled & Alternative Nuclear Fuels.
By Fuel Form: Fuel Assemblies & Conventional Fuel Products; Enriched Uranium Products; Uranium Concentrate & Conversion Products; Advanced Fuel Forms.
By Reactor Application: Pressurized & Boiling Water Reactors; Heavy Water & Other Thermal Reactors; High-Temperature & Gas-Cooled Reactors; Fast & Molten-Salt Reactors; Other Advanced Reactors.
By Fuel-Cycle Service: Uranium Conversion & Enrichment; Uranium Mining & Milling; Nuclear Fuel Fabrication; Spent Fuel, Reprocessing & Recycled Fuel; HALEU & Advanced Fuel Supply Chain; Other Nuclear Fuel Services.
Regional Markets: North America; Europe; Asia-Pacific; Latin America; Middle East & Africa.
Competitive Landscape
The competitive landscape combines integrated uranium and fuel-cycle groups, enrichers, fuel fabricators and state-owned national champions. TVEL alone accounts for about one-third of the world market for enrichment services, while Urenco, Orano, Centrus and CNNC compete in enrichment, and Westinghouse, Framatome, GNF, KEPCO Nuclear Fuel, Mitsubishi Nuclear Fuel, ENUSA, BWXT and Ulba-FA compete in fabrication. Companies are increasingly focused on securing long-term contracts, expanding licensed capacity, qualifying higher-enrichment and advanced fuels, and reducing dependence on Russian supply. Major industry participants include:
- Cameco Corporation
- Orano
- ROSATOM / TVEL
- Urenco
- China National Nuclear Corporation (CNNC)
- Westinghouse Electric Company LLC
- Framatome
- Kazatomprom
- Centrus Energy Corp.
- BWX Technologies, Inc. (BWXT)
- Global Nuclear Fuel (GNF)
- KEPCO Nuclear Fuel Co., Ltd.
- Mitsubishi Nuclear Fuel Co., Ltd.
- ENUSA Industrias Avanzadas, S.A.
- Ulba Metallurgical Plant / Ulba-FA
Recent Developments
- 30 September 2026: Cameco’s month-end industry price indicators showed the uranium spot price at US$89.63 per pound and the long-term price at US$96.50 per pound.
- 3 August 2026: Kazatomprom reiterated its 2026 production guidance of 27,500-29,000 tU (100% basis) after first-half production rose year on year.
- 24 July 2026: Germany approved the expansion of Framatome subsidiary Advanced Nuclear Fuels’ Lingen plant to produce VVER-1000 fuel for EU reactors.
- 1 July 2026: Centrus signed the contract finalising its US$900 million DOE task order to deploy commercial-scale HALEU enrichment at Piketon, Ohio, having produced more than 1,900 kg of HALEU under its demonstration contract.
- 2 June 2026: Urenco USA announced a 2.1 million SWU expansion of its Eunice, New Mexico enrichment plant, with the first cascades starting production in 2032.
- June 2026: The U.S. Nuclear Regulatory Commission (NRC) approved Framatome to raise the enrichment limit at its Richland, Washington fuel plant to just under 10% U-235 and to fabricate TRISO fuel.
- 25 May 2026: Urenco and Antares Nuclear signed what Urenco described as the world’s first multi-year commercial HALEU supply contract.
- 21 May 2026: The NRC accepted Orano’s licence application for the US$5 billion Project IKE enrichment plant in Oak Ridge, Tennessee for a 12-month review, with a decision due by 30 April 2027.
- 2 March 2026: Cameco agreed to supply nearly 22 million pounds of U3O8 to India’s Department of Atomic Energy between 2027 and 2035, in a contract valued at about US$1.9 billion.
Related Visiongain Market Reports
- Nuclear Power Plant Market Report 2025-2035
- Small Modular Reactor (SMR) Market Report 2025-2035
- Chemical, Biological, Radiological & Nuclear (CBRN) Defence Market Report 2025-2035
- Nuclear Waste Management Market Report 2024-2034
- Molten Salt Reactors Market Report 2022-2032
About Visiongain
Established in 1998, Visiongain is an independent publisher of analyst-led market intelligence, delivering data-driven research, forecasts, and strategic insight across global industries and emerging markets. Visiongain supports evidence-based decision-making for investment, procurement, and long-term strategic planning.
Media Contact
press@visiongain.com
+44 (0)20 7336 6100
www.visiongain.com