Electric Powertrain Market to reach US$257.09bn
14 August 2026.
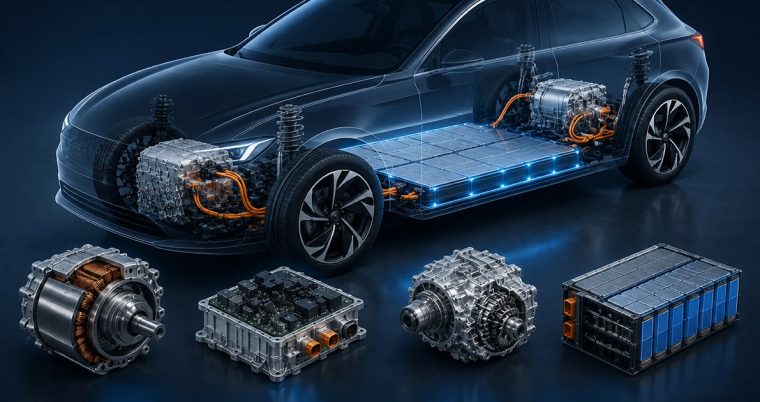
Visiongain has released its new Electric Powertrain Market Report 2026-2036, forecasting that the global market will grow from US$75.67 billion in 2026 to US$257.09 billion by 2036.
The market is forecast to expand at a compound annual growth rate (CAGR) of 13.0% between 2026 and 2036, building from a 12.7% CAGR between 2026 and 2031 to a 13.3% CAGR between 2031 and 2036, as integrated e-axle adoption, all-wheel-drive proliferation, and commercial-vehicle electrification scale up.
Key Market Growth Drivers & Industry Transformations
The EV electric powertrain market is undergoing a structural consolidation in which integration, efficiency, and supply-chain resilience are becoming the principal competitive dimensions. Visiongain’s research identifies four key catalysts driving market expansion:
- Shift Toward Integrated eDrives: Integrated Powertrain Systems (3-in-1 / 8-in-1 eDrives) are growing at a 13.6% CAGR, ahead of Discrete Powertrain Systems’ 12.6% CAGR, as automakers and Tier-1 suppliers combine the motor, inverter and gearbox into compact, lighter-weight modules. Within components, Integrated E-Axles/Drive Modules are the single fastest-growing category, expanding at a 14.2% CAGR to US$51.00 billion by 2036.
- Transition to Wide-Bandgap Traction Inverters: Traction Inverters (Si IGBT & SiC/GaN) are projected to grow at a 13.5% CAGR to US$65.86 billion by 2036, ahead of the overall market, as 800V architectures accelerate adoption of SiC and GaN power semiconductors over legacy silicon IGBTs.
- Rising All-Wheel Drive Adoption: All-Wheel Drive (AWD) is the fastest-growing drive-type segment at a 13.8% CAGR, reaching US$57.48 billion by 2036, as dual-motor configurations become standard on mid-market and premium BEVs.
- Electrification of Commercial Vehicles: Medium & Heavy Commercial Vehicles (M&HCVs) are the fastest-growing vehicle-type segment at a 15.5% CAGR, albeit from a smaller base (US$8.05 billion by 2036), as logistics and transit fleets accelerate electrified powertrain adoption.
Major Supplier Consolidation Reshapes the Competitive Landscape
The electric powertrain supply base has undergone significant corporate restructuring over the past two years. Schaeffler AG completed its merger with Vitesco Technologies Group AG on 1 October 2024, folding the former Vitesco E-Mobility business into Schaeffler’s divisional structure; full legal-entity integration across individual countries continues through 2027. Continental AG’s Automotive division was spun off as the independently listed AUMOVIO SE in September 2025. Most recently, American Axle & Manufacturing completed its acquisition of Dowlais Group plc, parent of GKN Automotive, on 3 February 2026; the combined business has since been rebranded Dauch Corporation.
This consolidation reflects the underlying economics of the transition: electrification compresses the addressable content available to legacy transmission and driveline specialists on pure-BEV platforms, pushing scale-driven M&A, even as the same suppliers invest to capture new integrated e-axle and power-electronics content.
Integration and Regional Localisation Accelerate
Magna International secured an 800V, 250kW two-speed integrated eDrive programme award from Chinese OEM Chery in July 2026, to be produced at Magna’s newly established Wuhu manufacturing facility, part of a broader localisation trend as OEMs and Tier-1 suppliers co-locate eDrive and e-axle production with vehicle assembly in China’s fast-growing domestic EV market. Magna’s dedicated hybrid drive system, DHD Duo, has separately reached series production with Chery on the Jetour G700, illustrating how established suppliers are pursuing both integrated BEV eDrives and dedicated hybrid architectures in parallel.
Discrete, transmission-centric architectures remain commercially significant even as integration accelerates. ZF Friedrichshafen and BMW Group signed a multi-billion-euro, long-term supply agreement in February 2026 for the continued development of ZF’s 8-speed automatic transmission (8HP), adapted specifically for electrified hybrid and plug-in hybrid drivetrains and extending into the late 2030s, confirming that dedicated hybrid transmission technology will continue generating substantial Tier-1 revenue well beyond the point at which integrated e-axles become standard on pure-BEV platforms.
Executive Quote
“The electric powertrain landscape is undergoing a structural consolidation where integration and scale are becoming the ultimate drivers of competitiveness,” stated a Senior Automotive Analyst at Visiongain.
“Over the next decade, Tier-1 suppliers that master multi-domain integration while successfully navigating the current wave of M&A-driven consolidation will secure the strongest competitive positions,” the analyst added.
Scope of the Visiongain Report
The 480+ page report provides robust quantitative and qualitative analysis across all key facets of the global market:
- By Architecture Layout: Discrete Powertrain Systems (Separated Motor/Inverter); Integrated Powertrain Systems (3-in-1 / 8-in-1 eDrives).
- By Drive Type: Front-Wheel Drive (FWD); Rear-Wheel Drive (RWD); All-Wheel Drive (AWD).
- By Vehicle Type: Passenger Cars; Light Commercial Vehicles (LCVs); Medium & Heavy Commercial Vehicles (M&HCVs); Other Vehicle Types.
- By Component: Electric Motors; Traction Inverters (Si IGBT & SiC/GaN); Integrated E-Axles / Drive Modules; On-Board Chargers (OBC) & DC-DC Converters; Transmissions & Reduction Gearboxes.
- By Propulsion Platform: Battery Electric Vehicles (BEVs); Plug-in Hybrid Electric Vehicles (PHEVs); Hybrid Electric Vehicles (HEVs); Fuel Cell Electric Vehicles (FCEVs); Range-Extended Electric Vehicles (REEVs); Other Propulsion Platforms.
- By Regional & Country Markets: North America, Europe, Asia Pacific, Latin America, and Middle East & Africa.
Competitive Landscape
The competitive environment is characterised by Tier-1 systems integrators investing in 3-in-1 and 8-in-1 e-axle architectures, SiC inverter capability, and commercial vehicle electrification programmes. Major market participants evaluated in the report include:
- Aisin Corporation
- AUMOVIO SE
- BorgWarner
- Robert Bosch GmbH
- Dauch Corporation (formerly American Axle & Manufacturing, incl. GKN Automotive)
- DENSO Corporation
- Astemo, Ltd.
- Hyundai Mobis
- Magna International Inc.
- Marelli Holdings
- Nidec Corporation
- Schaeffler AG (incl. former Vitesco Technologies)
- Valeo SE
- ZF Friedrichshafen AG
Recent Developments
- 03 Feb 2026 – American Axle & Manufacturing completes its acquisition of Dowlais Group plc (parent of GKN Automotive and GKN Powder Metallurgy); the combined business has since been rebranded Dauch Corporation, creating a global Tier-1 driveline and metal-forming supplier spanning 24 countries.
- 28 Jul 2026 – Magna International secures an 800V eDrive programme award with Chery, covering a 250kW two-speed integrated eDrive to be produced at Magna’s new Wuhu, China facility, alongside the DHD Duo dedicated hybrid drive system reaching series production on Chery’s Jetour G700.
- 02 Feb 2026 – ZF Friedrichshafen and BMW Group sign a multi-billion-euro, long-term supply agreement for the continued development of ZF’s 8-speed automatic transmission (8HP), adapted for electrified hybrid and plug-in hybrid drivetrains, extending into the late 2030s.
Related Reports
EV Battery Systems Market Report 2026-2036
Automotive Power Electronics & Semiconductor Market Report 2026-2036
EV Battery Recycling & Second-Life Market Report 2026-2036
Electric Vehicles (EV) Market Report 2025-2035
Solid-State Car Battery Market Report 2025-2035
About Visiongain
Established in 1998, Visiongain is an independent publisher of analyst-led market intelligence, delivering data-driven research, forecasts, and strategic insight across global industries and emerging markets. Visiongain supports evidence-based decision-making for investment, procurement, and long-term strategic planning.
Media Contact
press@visiongain.com
+44 (0)20 7336 6100
www.visiongain.com


